


A 1.5% flat rate with almost no exclusions, but is that still the best cashback deal in Singapore?
Mostly yes, with one honest catch. Cashback cards love to bury the catch in category caps and minimum spend. AMEX True Cashback skips most of that, but it isn’t the highest rate on the market.
⚡️ AMEX True Cashback Card at a Glance
| Feature | Detail |
|---|---|
| Base cashback rate | 1.5% on eligible purchases, no cap, no minimum spend |
| Welcome offer | 3% cashback on your first S$5,000 spend in the first 6 months (up to S$150) |
| Annual fee | S$174.40 (incl. GST), waived in year 1 |
| Exclusions | Just 2: GrabPay/stored value top-ups and SimplyGo |
| Best for | Simple, no-tracking local spend, especially at merchants that don’t take Visa/Mastercard |
📚 Table of Contents
- What Is the AMEX True Cashback Card?
- How Much Cashback Can You Actually Earn?
- What’s Excluded From AMEX True Cashback?
- AMEX True Cashback vs UOB Absolute Cashback
- Where AMEX True Cashback Actually Wins
- Is AMEX True Cashback Worth It?
- Annual Fee and Fee Waiver
- How Do You Redeem AMEX Cashback?
- How to Apply for AMEX True Cashback
- Why a Multi-Currency Card Still Beats It Overseas
- FAQ
What Is the AMEX True Cashback Card?
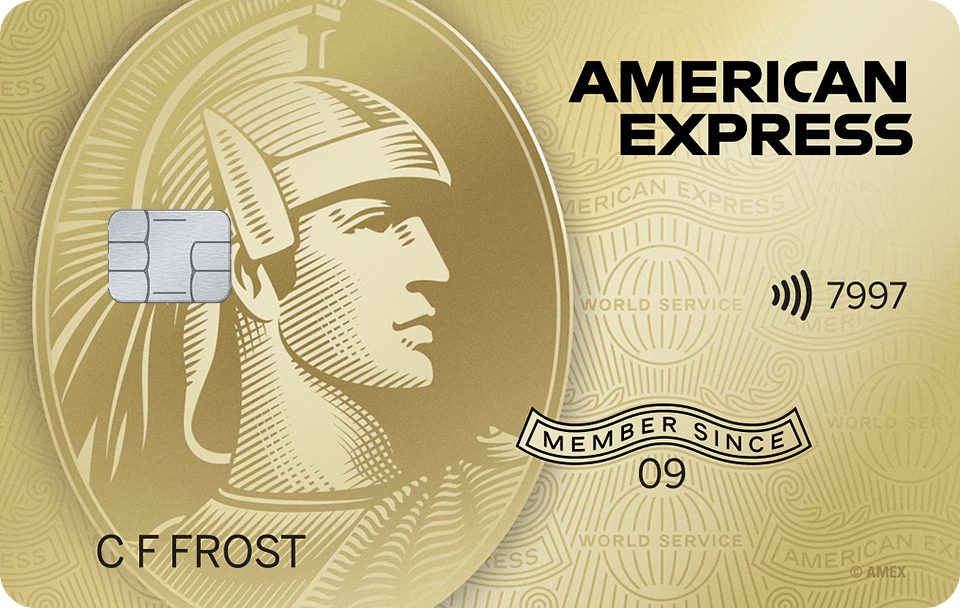
Image Credits: American Express
The AMEX True Cashback Card is American Express’s flat-rate cashback card for Singapore, built around a simple pitch: one rate, no categories to track, no minimum spend to hit.
- 1.5% cashback on eligible purchases, credited as a statement rebate the same month you spend
- No cap and no minimum spend, which puts it ahead of most “up to X%” tiered cards on the fine print
- Only 2 exclusions (GrabPay and SimplyGo), fewer than almost any other “no exclusions” card in Singapore
- S$174.40 annual fee, waived in the first year
📖 Related Guide: Wondering how it stacks up against every other flat-rate and tiered card in the market? Our Best Cashback Credit Card Singapore roundup ranks all 13.
How Much Cashback Can You Actually Earn?
The rate is straightforward: 1.5% on everything eligible, all the time, with a temporary bump for new cardholders.
Base Rate: 1.5% on Everything Eligible
Every eligible purchase earns 1.5% cashback, whether it’s a S$4 kopi or a S$4,000 laptop. There’s no monthly cap, no spending tier to climb, and no minimum transaction size. AMEX applies the rebate to your statement in the same billing cycle, so you’re not waiting weeks to see it land.
Welcome Bonus: 3% on Your First S$5,000
New cardholders earn 3% cashback on their first S$5,000 of eligible spend in the first 6 months, capped at S$150 total. Spend the full S$5,000 in that window, and you’ve effectively pocketed a S$150 sign-up bonus on top of your regular purchases.
Miss the window, and you drop straight to the standard 1.5%. If you’re chasing the full S$150, front-load big planned purchases (insurance renewals, flights, a laptop upgrade) into those first 6 months.
📖 Related Guide: Earning cashback is one way to cut costs. Avoiding fees entirely is another. See how YouTrip stacks up against credit cards for overseas spend.
What’s Excluded From AMEX True Cashback?
Only two things are excluded: GrabPay top-ups and SimplyGo. That’s it. Most “no exclusions” cashback cards still carve out charity, education, government payments, insurance, and utilities at a reduced rate. AMEX True Cashback doesn’t.
| Category | Cashback Status |
|---|---|
| GrabPay and other stored value top-ups | Excluded since April 2023 |
| SimplyGo (transit top-ups and fare payments) | Excluded since May 2025 |
| Charity, education, insurance, government payments, utilities | Full 1.5% (not reduced, unlike most competitors) |
| AXS bill payments (utilities, town council, income tax) | Full 1.5%, where AXS accepts AMEX |
| Hospital bills (where AMEX is accepted) | Full 1.5% |
Two exclusions is unusually narrow for this card category. UOB Absolute Cashback, by comparison, drops charity, education, government, healthcare, utilities, and professional services to 0.3%. It adds its own GrabPay cut on top.
If you regularly pay bills, donate by card, or use AXS for payments, AMEX True Cashback keeps the full rate. A lot of “flat rate” cards quietly don’t.
📖 Related Guide: Want to see how a cashback card stacks up against a digital-bank option instead? Our YouTrip vs MariBank comparison breaks down overseas spend on both.
AMEX True Cashback vs UOB Absolute Cashback
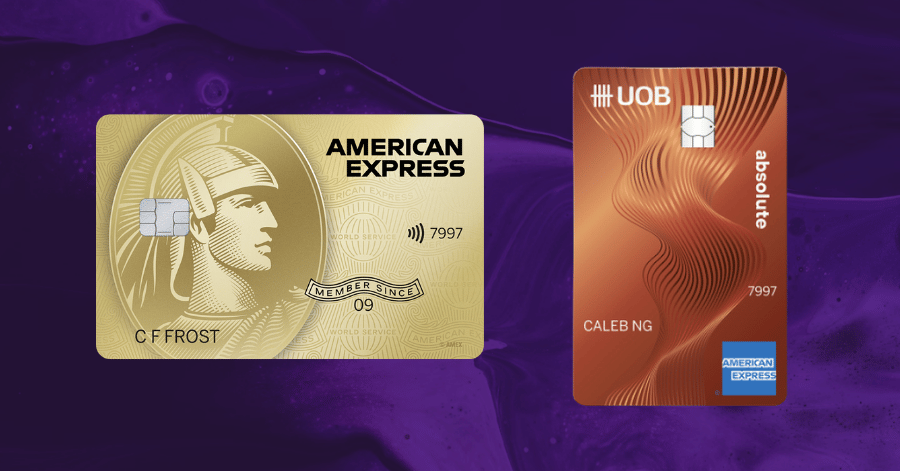
Both cards market themselves as “no exclusions” cashback cards, and both readers cross-shop them constantly. They’re close, but the numbers pull in different directions depending on what you spend on.
| AMEX True Cashback | UOB Absolute Cashback | |
|---|---|---|
| Base rate | 1.5%, no cap | 1.7%, no cap |
| Annual fee | S$174.40 (waived year 1) | S$196.20 (waived year 1) |
| GrabPay top-up | Not eligible | 0.3% since January 2023 (local); overseas Grab top-ups cut to 0.3% from 4 September 2026 |
| Charity / education / government / healthcare / utilities | Full rate | Reduced to 0.3% |
| Welcome offer | 3% on first S$5,000 (6 months) | Promotional up to 2% on contactless spend (4 Aug 2026 to 31 Jan 2027) |
UOB Absolute earns a higher headline rate (1.7% vs 1.5%), but that gap narrows or reverses once you spend in UOB’s reduced-rate categories. On S$1,000 of eligible spend, UOB pays S$17 against AMEX’s S$15. On S$1,000 of spend at a 0.3% category, UOB pays S$3 while AMEX still pays the full S$15.
Neither card beats the other outright; it depends on what you spend on. UOB Absolute suits someone whose spending is everyday retail and dining, where the 1.7% rate applies cleanly. AMEX True Cashback suits someone whose spend includes bill payments, insurance, or donations, where its narrower exclusion list keeps more of the rate intact.
📖 Related Guide: If neither card is a clean fit, our best travel credit cards in Singapore guide widens the shortlist to cards built for overseas spend.
Where AMEX True Cashback Actually Wins
AMEX True Cashback links to AMEX Pay QR, American Express’s own QR payment rail. Some hawker stalls and neighbourhood provision shops accept it alongside PayNow and GrabPay.
That’s a use case competitors don’t cover. A Visa or Mastercard-only cashback card earns nothing at a stall that only takes cash, PayNow, or AMEX Pay QR. A True Cashback holder tapping that QR code still earns the full 1.5% at spots where most other cashback cards earn zero.
It’s not a reason to get the card on its own. Coverage varies by stall, and it’s worth checking the AMEX app for which nearby merchants show the QR code before defaulting to cash.
📖 Related Guide: For everyday spend beyond hawker stalls, see how True Cashback’s flat rate compares against a multi-currency card in our roundup.
Is AMEX True Cashback Worth It?
Yes, if you want one flat rate and don’t want to track spending categories. It’s a weaker pick if you’re chasing the single highest cashback number on the market.
✅ Where It Makes Sense
- You want simplicity over the highest possible rate, with no monthly tracking
- Your spend touches bill payments, insurance, or donations, where competitors quietly cut the rate
- You’re a light-to-moderate spender who won’t hit UOB Absolute’s higher-rate categories often enough to make up the fee gap
❌ Where It Falls Short
- You spend heavily on Grab or public transport top-ups, both excluded here
- You want the single highest flat rate. UOB Absolute’s 1.7% base beats it on straightforward retail and dining
- You spend a lot overseas. A cashback card isn’t the right tool for that job, regardless of issuer
📖 Related Guide: Comparing AMEX True Cashback against a multi-currency card instead of another credit card? See how YouTrip stacks up against Trust on overseas spend.
Annual Fee and Fee Waiver
The annual fee is S$174.40 (inclusive of 9% GST), waived automatically for the first year. AMEX doesn’t publish a standing spend threshold to waive it again from year 2 onward, unlike some miles cards that waive the fee at a fixed annual spend.
Supplementary cards are more generous than most: the first 2 are permanently free, with each additional supplementary card costing S$87.20 a year. If you’re sharing the card with a partner or family, the free supplementary cards add up.
📖 Related Guide: If an annual fee puts you off entirely, our UOB One Account review covers a fee-free way to earn on your everyday balance instead.
How Do You Redeem AMEX Cashback?
There’s nothing to redeem in the usual sense. AMEX True Cashback pays out as a statement credit, not points or miles you have to transfer or convert.
- Cashback earned on a purchase is credited straight to your card statement, usually within the same billing cycle
- It reduces the amount you owe that month; there’s no separate cashback wallet or app to withdraw from
- There’s no minimum threshold to “unlock” before it pays out, and nothing expires because it’s never sitting as a points balance in the first place
If you’re used to miles cards where you actively transfer or book redemptions, this is simpler by design. The cashback just quietly lowers your bill.
📖 Related Guide: Wise skips cashback entirely and focuses on transfers instead. Our YouTrip vs Wise comparison breaks down which approach costs less on a real trip.
How to Apply for AMEX True Cashback
- Age: 21 and above for the principal card (18+ for supplementary cardholders)
- Minimum income: over S$30,000 a year for Singapore Citizens and PRs, and over S$60,000 a year for foreigners
- Documents: NRIC or passport, plus proof of income (latest payslip or Notice of Assessment) if requested
Apply directly through the AMEX Singapore website; approval timelines vary by applicant profile.
📖 Related Guide: Applying for a second card to pair with True Cashback? Our YouTrip overview covers what it is and how sign-up works.
Why a Multi-Currency Card Still Beats It Overseas
AMEX True Cashback is built for local Singapore dollar spend, and it does that job well. It isn’t built for overseas spend, and neither is any other SGD cashback card. AMEX charges a foreign transaction fee on top of whatever exchange rate it applies, the same as most bank-issued cashback and miles cards.
That’s where a multi-currency wallet like YouTrip does a different job. YouTrip charges no foreign transaction fee and bills overseas taps at the Mastercard wholesale rate, the same rate banks use between themselves. For cash, the first S$400 of overseas ATM withdrawals each calendar month is free, then a flat 2% after that.
AMEX True Cashback and YouTrip aren’t solving the same problem. Keep AMEX True Cashback for everyday Singapore spend where its narrow exclusion list keeps earning, and switch to YouTrip the moment you land overseas.
📖 Related Guide: For the full breakdown of wholesale rates versus what banks quote you, see how to get the best exchange rate in Singapore.
FAQ
It’s worth it if you want a simple 1.5% flat rate with almost no exclusions and don’t want to track spending categories. It’s a weaker fit if you’re chasing the single highest cashback rate: UOB Absolute’s 1.7% base beats it on plain retail spend. It’s also weaker if Grab and transit top-ups make up a big share of your spending.
Only 2 things: GrabPay and other stored value top-ups (excluded since April 2023) and SimplyGo transit payments (excluded since May 2025). Charity, education, government payments, insurance, and utilities all still earn the full 1.5%, categories most competing “no exclusions” cards quietly cut.
New cardholders earn 3% cashback on their first S$5,000 of eligible spend within 6 months of approval, up to a maximum of S$150. After that window, the rate drops to the standard 1.5%.
You don’t redeem it in the traditional sense. Cashback is credited straight to your card statement as a rebate, usually within the same billing cycle, and lowers what you owe that month. There’s no points wallet, no conversion step, and nothing to expire.
True Cashback is AMEX Singapore’s dedicated cashback card. Other AMEX cards, like the Singapore Airlines KrisFlyer Credit Card, earn miles instead. If cashback specifically is the goal, True Cashback is the one built for it.
Yes, it charges the standard foreign transaction fee on overseas spend, the same as most bank-issued cashback cards. For overseas spend specifically, a no-FX-fee multi-currency card like YouTrip works out cheaper than earning 1.5% cashback while also paying a foreign transaction fee on top.
The straightforward pick for simple, no-fuss cashback
AMEX True Cashback isn’t the highest-earning cashback card in Singapore, but it’s one of the most honest about what it actually excludes. If you want one flat rate, minimal fine print, and full earnings on bill payments most cards quietly cut, that’s the card to carry. For everyday local spend, pair it with your regular banking. For anything overseas, that’s a different card’s job entirely.
Not a YouTrooper yet? Singapore’s go-to multi-currency wallet helps you save with great FX rates and zero fees. Skip the money changer and get a free YouTrip card + S$5 YouTrip credits with code YTBLOG5.
Then, head over to our YouTrip Perks page for exclusive offers and promotions, we promise you won’t regret it. Join our Telegram (@YouTripSG) and Community Group (@YouTripSquad) for travel tips, event invites, and more!
Happy travels!