


A flat 1.7% with no cap sounds simple, until you hit one of the 7 categories that earn a lower rate
Cashback cards usually hide the catch in spending tiers and category caps. UOB Absolute skips most of that: one rate, no minimum spend, no cap. But UOB has trimmed the “no exclusions” pitch three times since the card launched, and the current terms are narrower than the marketing headline suggests.
⚡️ TL;DR: UOB Absolute Cashback Card at a Glance
| Feature | Detail |
|---|---|
| Base cashback rate | 1.7% on eligible local and overseas spend, no cap, no minimum spend |
| Current promo | Up to 2% on contactless card taps (physical card only), 4 Aug 2026–31 Jan 2027 |
| Annual fee | S$196.20 (incl. GST), waived year 1 |
| Reduced-rate categories | 0.3% on charity, education, government, healthcare, utilities, professional services, Grab wallet top-ups |
| Best for | Fuss-free spend on categories other cashback cards exclude, like insurance and bills |
📚 Table of Contents
- What Is the UOB Absolute Cashback Card?
- How Does UOB Absolute Cashback Actually Work?
- What’s Really Included (and What’s Been Cut Since Launch)
- UOB Absolute Cashback Card vs UOB One Card
- UOB Absolute vs AMEX True Cashback vs Citi Cashback Plus
- The GrabPay Top-Up Trick: Using It Where AMEX Isn’t Accepted
- Is the UOB Absolute Cashback Card Good? Who It’s Actually For
- Eligibility and How to Apply
- Why a Multi-Currency Wallet Still Beats It Overseas
- FAQ
What Is the UOB Absolute Cashback Card?
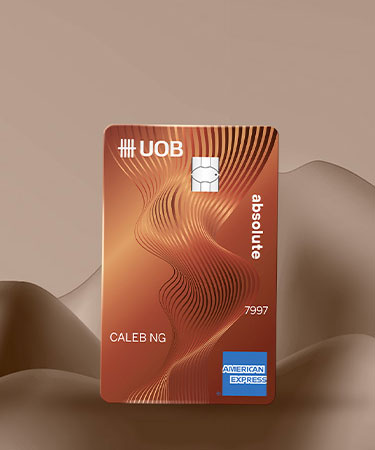
Image Credits: UOB Singapore
Yes, it’s UOB’s flat-rate cashback card, co-branded with AMEX. One pitch: a single 1.7% rate, no minimum spend, no cap on what you can earn.
- 1.7% cashback on eligible local and overseas spend, credited automatically, no categories to track
- No minimum spend and no cap, so a S$20 grocery run and a S$5,000 laptop both earn the same rate
- AMEX-issued, which means a 15-digit card number and narrower merchant acceptance than a Visa or Mastercard
- S$196.20 annual fee (incl. GST), waived in the first year
- New cardholders who apply during the current promo also get a S$100 Samsung e-voucher on meeting the minimum spend requirement
- The card also carries a standing 6-month complimentary Founders Card membership, a travel perks programme with Hilton Honors Gold-equivalent status
📖 Related Guide: Want the full rundown on every flat-rate and tiered cashback card in the market? Our Best Cashback Credit Card Singapore roundup ranks all 13.
How Does UOB Absolute Cashback Actually Work?
The rate is straightforward on paper: 1.7% on almost everything, credited to your statement, no redemption steps.
The 1.7% Flat Rate: What Counts and What Doesn’t
Every eligible transaction earns 1.7% cashback, whether it’s charged locally or overseas. UOB pays this out as an automatic statement credit, so there’s nothing to redeem and no points balance to manage. NETS transactions, 0% instalment plans, cash advances, and any UOB fees or charges don’t earn cashback, the same standard exclusions most cards carry.
Annual Fee and How to Get It Waived
The annual fee is S$196.20 (inclusive of GST), waived automatically in the first year. Supplementary cards cost S$98.10 each from the second card onward. UOB doesn’t publish a standing spend threshold to waive the fee again from year 2, but its automated hotline routinely grants a waiver on request. Call before the fee posts, ask, and it usually goes through without a fight.
📖 Related Guide: Weighing an annual fee against a no-fee alternative? Our YouTrip vs credit cards breakdown compares the real costs side by side.
What’s Really Included (and What’s Been Cut Since Launch)
UOB advertises “no spend exclusions,” but that claim has been narrowed three times since the card launched, and the current terms carve out 7 categories at a reduced rate.
| Category | Cashback Status |
|---|---|
| General local and overseas retail, dining, groceries | Full 1.7% |
| Contactless card taps (4 Aug 2026–31 Jan 2027 promo) | Up to 2% (1.7% base + 0.3% bonus, physical card tap only, no cap) |
| Charity, education, government, healthcare, utilities, professional services (local) | Reduced to 0.3%, since 6 May 2024 |
| The same 7 categories, overseas | Reduced to 0.3%, since 4 September 2026 |
| Grab wallet top-ups (local) | Reduced to 0.3%, since 15 January 2023 |
| Grab wallet top-ups (overseas) | Reduced to 0.3%, since 4 September 2026 |
| NETS transactions, instalment plans, cash advances, UOB fees | Not eligible |
The Grab wallet cut actually came first, back in January 2023, well before the other 6 categories. UOB cut the local rate on the remaining 6 categories in May 2024, then extended the same cut to overseas spend (plus overseas Grab top-ups) in September 2026. If a category earns full rate today, that’s not a guarantee it stays that way.
Insurance premiums and hospital bills aren’t on the reduced list, so they still earn the full 1.7%. UOB Absolute beats most competitors here: they cut these categories to zero, UOB just lowers the rate.
📖 Related Guide: Comparing this card against a digital-bank option instead? Our YouTrip vs MariBank comparison breaks down overseas spend on both.
UOB Absolute Cashback Card vs UOB One Card
Both cards are from UOB, but one rewards effort and the other rewards none. UOB Absolute pays a flat rate for doing nothing, while UOB One pays more only if you hit a spend tier.
| UOB Absolute Cashback | UOB One Card | |
|---|---|---|
| Base rate | 1.7%, no minimum spend, no cap | 3.33% to 5%, tiered by monthly spend |
| Additional cashback | None beyond the current contactless promo | Up to 5% extra on daily essentials (7-Eleven, Cold Storage, Giant, Guardian) and Grab |
| Effective max rate | 1.7% (up to 2% during the current promo) | Up to 10% on qualifying categories |
| Tracking required | None | Consistent S$500/S$1,000/S$2,000 monthly spend across 3 months in a quarter |
| What happens if you miss the tier | Nothing, rate stays flat | The entire quarter’s cashback drops to the lowest qualifying tier |
UOB One’s headline 10% looks unbeatable, but it only pays out if you track spend across a full quarter and hit the tier every single month. Miss one month and the whole quarter reverts to the lowest tier. UOB Absolute pays a flat 1.7% with zero tracking, which suits anyone who doesn’t want to run a monthly spreadsheet just to keep a cashback rate.
📖 Related Guide: Wondering how UOB One measures up as a savings account too? See our UOB One Account review.
UOB Absolute vs AMEX True Cashback vs Citi Cashback Plus
UOB Absolute, AMEX True Cashback, and Citi Cashback Plus are the three worth comparing head-to-head. All three are flat-rate, no-minimum-spend cashback cards with no monthly tiers to chase. That puts them in a different bracket from category-capped options like HSBC Revolution and Trust Bank’s Freedom card, which trade the flat rate for a higher percentage on a narrower, opt-in set of spending categories.
| UOB Absolute Cashback | AMEX True Cashback | Citi Cashback Plus | |
|---|---|---|---|
| Base rate | 1.7%, no cap | 1.5%, no cap | 1.6%, no cap |
| Annual fee | S$196.20 (waived year 1) | S$174.40 (waived year 1) | S$192.60 (waived year 1) |
| Reduced-rate categories | 7 categories at 0.3% (see above) | Only 2: GrabPay and SimplyGo | Insurance, education, and several bill categories excluded |
| Card network | AMEX, narrower merchant acceptance | AMEX, narrower merchant acceptance | Mastercard, widely accepted |
UOB Absolute earns the highest headline rate of the three, but AMEX True Cashback keeps more categories at full rate. Insurance, education, government, and utilities all earn the full 1.5% on AMEX, while UOB drops the same categories to 0.3%.
On S$1,000 of spend in one of those 7 UOB-reduced categories, UOB pays S$3 while AMEX still pays S$15. On S$1,000 of general retail spend, UOB pays S$17 against AMEX’s S$15. Which one wins depends entirely on what the spend is for.
Someone whose spend is mostly everyday retail and dining gets more from UOB Absolute’s higher base rate. Someone paying recurring bills, insurance premiums, or education fees keeps more of the rate with AMEX True Cashback’s narrower exclusion list.
📖 Related Guide: For the full breakdown against AMEX True Cashback specifically, read our AMEX True Cashback Card review.
The GrabPay Top-Up Trick: Using It Where AMEX Isn’t Accepted
Patchy AMEX acceptance is UOB Absolute’s biggest limitation. The most common fix comes from cardholders themselves: top up GrabPay.
The Mastercard Workaround
Not every merchant in Singapore accepts AMEX. Insurers, hospitals, and Town Councils are frequent holdouts. The fix: top up your GrabPay wallet using the UOB Absolute card, then pay with the GrabPay Mastercard, which is accepted almost everywhere the AMEX card isn’t.
This still solves the acceptance problem today, but don’t expect it to earn much cashback on the way through. UOB cut Grab wallet top-ups to 0.3% back on 15 January 2023, so the top-up itself has paid the reduced rate for years. Use it for merchant acceptance, not for the rate.
Why the Old “2.9% Effective Cashback” Trick No Longer Works
A stacking trick that circulated widely among Singapore finance creators around 2021 to 2022 combined UOB Absolute’s Grab top-up with GrabRewards’ old Platinum tier, which paid extra points on GrabPay spend, for a combined effective return creators quoted at around 2.9%. Two changes have since closed that gap.
First, UOB cut Grab wallet top-ups to 0.3% in January 2023, years before this cut applied to any other category. Second, Grab discontinued its tiered GrabRewards program (Member, Silver, Gold, Platinum) in early 2026 and replaced it with GrabCoins, a flat 0.3% back on GrabPay wallet spend with no tier to unlock.
There’s no Platinum tier left to stack, and the Grab side of the trick pays a fraction of what it used to. If you see this figure quoted anywhere today, treat it as outdated.
One more trick to ignore: some creators combine a GrabPay top-up with a separate fintech card’s time-limited transit cashback promo to claim figures north of 20% on public transport spend. That relies on a promotional cap (often S$10/month) on a third-party card, not on UOB Absolute itself, and it shouldn’t be read as a repeatable strategy.
📖 Related Guide: If you’d rather skip workarounds entirely, see how a multi-currency card compares in our roundup.
Is the UOB Absolute Cashback Card Good? Who It’s Actually For
Yes, if you regularly spend in categories other cashback cards exclude outright. It’s a weaker pick if you’re chasing the single highest rate on ordinary retail spend. If cashback isn’t the priority at all, our best Singapore credit cards roundup covers miles and rewards cards too.
✅ Where It Makes Sense
- You pay insurance premiums or hospital bills by card, which still earn the full 1.7% here (most competing cards exclude these outright rather than reducing the rate)
- You want zero tracking, no spend tiers, no quarterly minimums to hit
- You’re a light-to-moderate spender who won’t benefit from UOB One’s higher but tier-gated rates
❌ Where It Falls Short
- A meaningful share of your spend sits in the 7 reduced-rate categories (charity, education, government, healthcare, utilities, professional services, Grab top-ups), where you now earn 0.3% instead of 1.7%
- You need wide merchant acceptance. The AMEX network is narrower than Visa or Mastercard, and mobile contactless payment (Apple Pay, Google Pay, Samsung Pay) isn’t supported on this card at all
- You spend heavily overseas. A cashback card isn’t built for FX savings, regardless of issuer
Best for Insurance, Hospital Bills, and Town Council Payments
This is where UOB Absolute beats most other cashback cards: it still pays something on categories they cut to zero. Competing “no exclusions” cashback cards routinely carve insurance, education, and government payments out entirely. UOB Absolute still pays a reduced 0.3% on these rather than zero, which beats earning nothing, even if it’s a step down from the advertised 1.7%.
📖 Related Guide: Comparing this against a multi-currency card for everyday spend instead? Our best travel credit cards in Singapore guide widens the shortlist.
Eligibility and How to Apply
- Age: 21 and above
- Minimum income: S$30,000 a year for Singapore Citizens and PRs under 55, S$15,000 a year for those 56 and above, or S$40,000 a year for foreigners
- Alternative to income: a Fixed Deposit of at least S$10,000 with UOB qualifies in place of the income requirement
- Documents: NRIC or passport, plus proof of income if requested
Apply directly through the UOB Singapore website; approval timelines vary by applicant profile.
📖 Related Guide: Applying for a second card to pair with UOB Absolute overseas? Our YouTrip overview covers what it is and how sign-up works.
Why a Multi-Currency Wallet Still Beats It Overseas
UOB Absolute pays a flat 1.7% no matter what currency you spend in, which sounds like it covers overseas spend too. It doesn’t cover the exchange rate, which is the part that actually costs you money.
A cashback card gives you a rebate in Singapore dollars, but the underlying conversion still runs through whatever rate and foreign transaction fee your issuer applies at the point of sale. That’s a separate cost from the cashback earned, and it can easily exceed the 1.7% rebate on its own.
A multi-currency wallet like YouTrip solves that specific problem. No foreign transaction fee, and every overseas tap bills at the Mastercard wholesale rate, the same rate banks use between themselves.
For cash, the first S$400 of overseas ATM withdrawals each calendar month is free with YouTrip, then a flat 2% after that. One creator in this card’s own community described exactly this pairing. They top up a YouTrip wallet using UOB Absolute before a trip, earning cashback on the top-up while getting the wholesale rate on the spend itself.
UOB Absolute and YouTrip solve different problems: one is for local spend, the other is for spending in another currency. Keep UOB Absolute for local bills and insurance where it earns cleanly, and switch to YouTrip the moment you’re spending overseas.
📖 Related Guide: For the full breakdown of wholesale rates versus what banks quote you, see how to get the best exchange rate in Singapore.
FAQ
It’s a solid pick if your spend regularly includes insurance, hospital bills, or other categories most competitors exclude outright, since UOB Absolute still pays 0.3% on these rather than nothing.
It’s a weaker fit if you’re chasing the single highest rate on ordinary retail spend, or if a large share of your spend sits in one of the 7 categories UOB reduced to 0.3% since 2024 and 2026.
No. UOB confirms that all UOB AMEX cards, including Absolute Cashback, are eligible for physical contactless taps but not mobile contactless payments like Apple Pay, Google Pay, or Samsung Pay. You’ll need to tap the physical card or use it online.
Cash advances are explicitly excluded from earning cashback and typically carry a separate cash advance fee and interest charge from the moment of withdrawal, the same as most credit cards. It’s not a card built for cash withdrawals.
UOB Absolute pays a flat 1.7% with no tracking required. UOB One pays up to 10% on selected categories but requires hitting a consistent monthly spend tier across a full quarter, and missing one month drops the whole quarter to the lowest tier.
Absolute suits hands-off spenders; One suits anyone willing to track a few categories closely. If miles matter more to you than cashback, our best miles card guide covers that comparison separately.
The fee is automatically waived in the first year. From year 2, call UOB’s customer service hotline before the fee posts to your statement and request a waiver. It isn’t guaranteed every year, but it’s routinely granted on request.
Seven categories: charity, education, government, healthcare, utilities, professional services, and Grab wallet top-ups. Grab top-ups dropped first, cut to 0.3% locally from 15 January 2023.
The other six categories followed later, cut to 0.3% locally from 6 May 2024, with the same reduction extended to overseas spend (including overseas Grab top-ups) from 4 September 2026.
The flat-rate card that’s narrower than it advertises
UOB Absolute Cashback still earns the highest flat rate of Singapore’s no-minimum-spend cashback cards, and it’s genuinely useful for bills and insurance that most competitors exclude outright. Just don’t expect the “no exclusions” pitch to hold up the way it did when the card launched. For everyday local spend, this card does its job cleanly. The moment you’re spending overseas, that’s a different card’s job entirely.
Not a YouTrooper yet? Singapore’s go-to multi-currency wallet helps you save with great FX rates and zero fees. Skip the money changer and get a free YouTrip card + S$5 YouTrip credits with code YTBLOG5.
Then, head over to our YouTrip Perks page for exclusive offers and promotions, we promise you won’t regret it. Join our Telegram (@YouTripSG) and Community Group (@YouTripSquad) for travel tips, event invites, and more!
Happy travels!